
Bloom Energy (BE) Q3 Earnings Preview: AI Data Center-Driven Growth Validation and Options Volatility
 2026/10/22 06:30
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
1. Investment Highlights
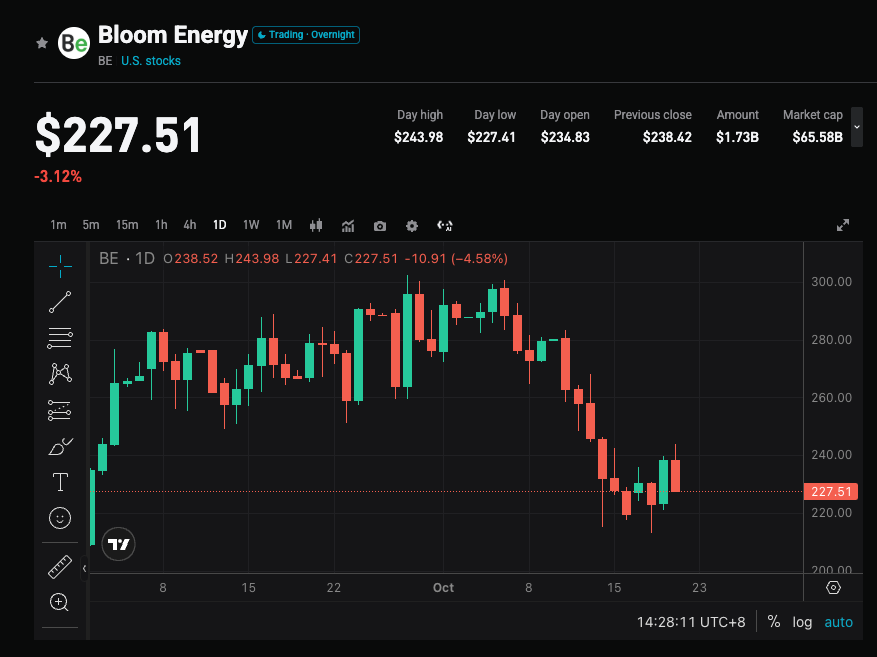
Bloom Energy will report its fiscal 2026 third-quarter results after the U.S. market close on October 22, 2026. Wall Street consensus expects revenue of approximately $1.07 billion (about +106% YoY, versus roughly $519 million in the prior-year period) and adjusted EPS of about $0.69 (about +360% YoY, versus $0.15). Options markets are pricing in an implied move of roughly 10.7% (based on a recent close near $222, implying a range of approximately $197–$248). The stock has surged about 166% year-to-date, with the market closely watching whether demand for solid oxide fuel cells (SOFCs) from AI data centers can continue converting into revenue and profits, and whether full-year guidance will be raised again.
Focus 1: AI Data Center Demand and Hyperscaler Customer Deployments
The AI compute boom has created bottlenecks in grid connections and gas turbine deliveries, making Bloom’s on-site fuel cells a rapid-deployment alternative. The company has received validation from major U.S. hyperscalers, with gigawatt-scale collaborations advancing with customers such as Oracle, and Brookfield’s financing framework expanded to as much as $25 billion. The market will focus on order and delivery momentum this quarter, as well as whether the contribution from hyperscale customers continues to rise, to confirm that demand is shifting from a thematic story to scaled monetization.
Focus 2: Capacity Expansion and Average Selling Price Improvement
The company is advancing toward 2 GW of annual production capacity (roughly doubling prior levels), with higher site content expected to support average selling prices. Institutions such as Truist expect strong year-over-year demand to support revenue and profits, while Baird sees further long-term upside if capacity expands to 6 GW, 8 GW, or even 10 GW. The earnings report will test whether the capacity ramp is progressing smoothly and how product mix optimization contributes to gross margins.
Focus 3: Profitability and the “Beat-and-Raise” Momentum
The company has delivered revenue and EPS beats for multiple consecutive quarters, with Q2 revenue of roughly $1.07 billion (strong year-over-year growth) and adjusted EPS of about $0.78. Full-year guidance has already been raised to revenue of $3.9–$4.2 billion and adjusted EPS of $2.55–$2.85. The market is watching whether this quarter delivers another clear beat and an upward revision to the full-year outlook, to confirm that high growth is sustainable rather than a one-time delivery spike.
Focus 4: Valuation Digestion and Options-Implied Volatility
After the sharp year-to-date rally, valuation remains elevated. The Moderate Buy consensus price target is around $297, implying roughly 28–33% upside. The average absolute post-earnings move over the last four reports was about 12.95% (with gains in three of the four). The 10.7% options-implied move suggests the potential for significant two-way volatility in the near term, with management’s commentary on second-half deliveries and capacity serving as a key sentiment driver.
3. Risks and Opportunities
Upside Catalysts:
- Revenue and adjusted EPS significantly exceed consensus (particularly if revenue approaches or exceeds $1.1 billion), accompanied by a raise to full-year guidance.
- Details of new hyperscaler orders or gigawatt-scale project deployments come in better than expected, with a more aggressive capacity expansion timeline.
- Gross margins remain in the mid-to-high range (prior non-GAAP gross margins were around 30%+), demonstrating continued scale benefits and cost control.
Downside Risks:
- Results merely meet or slightly miss expectations, with full-year guidance left unchanged or accompanied by cautious language, triggering profit-taking amid elevated valuations.
- High customer concentration (a single customer previously accounted for a large share of revenue) leads to slower delivery pace or weaker order conversion than expected.
- Capacity ramp-up or supply-chain bottlenecks affect deliveries, amplifying downside amid broader tech-sector volatility.
4. Trading Strategy
Bull Case: If revenue and profits clearly beat expectations, and management raises full-year guidance while providing positive updates on capacity and customer progress, it could reinforce Bloom’s positioning as a core AI power solution provider and support further valuation recovery.
Bear Case: If results only meet consensus, guidance is cautious, or customer deployment details are limited, the combination of high valuation and options-implied volatility could trigger short-term selling, especially after the stock’s substantial recent gains.
Key Metrics to Watch:
- Total revenue and year-over-year / sequential growth
- Adjusted EPS and gross margin performance
- Whether full-year revenue and EPS guidance is raised
- Capacity expansion progress and hyperscaler customer contribution / order trends
Tactical Takeaway: A clear beat with positive guidance could present opportunities on pullbacks; if results are merely in-line or guidance is soft, be mindful of near-term volatility and avoid chasing strength. Given the elevated options-implied move, position sizing and stop-loss levels should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
SI business accelerates outbreak and consolidates growth trend! UBS raises target for SpaceX (SPCX.US) to $230
UBS believes that SpaceX continues to meet the market's high expectations for the company, and this trend is expected to continue. UBS gives SpaceX a "Buy" rating with a 12-month price target of $230.
Elon Musk publicly supports the merger of SpaceX (SPCX.US) and Tesla (TSLA.US); insiders worry negotiations might change.
This week, Musk publicly expressed support for a potential merger between SpaceX and Tesla, but this statement has made insiders involved in the discussion uneasy. They worry that such remarks may invite scrutiny from shareholders and delay the transaction process for several weeks.
Analysis - How the Merged SpaceX-Tesla Will Address Its China Issues
Crypto prices
More


